
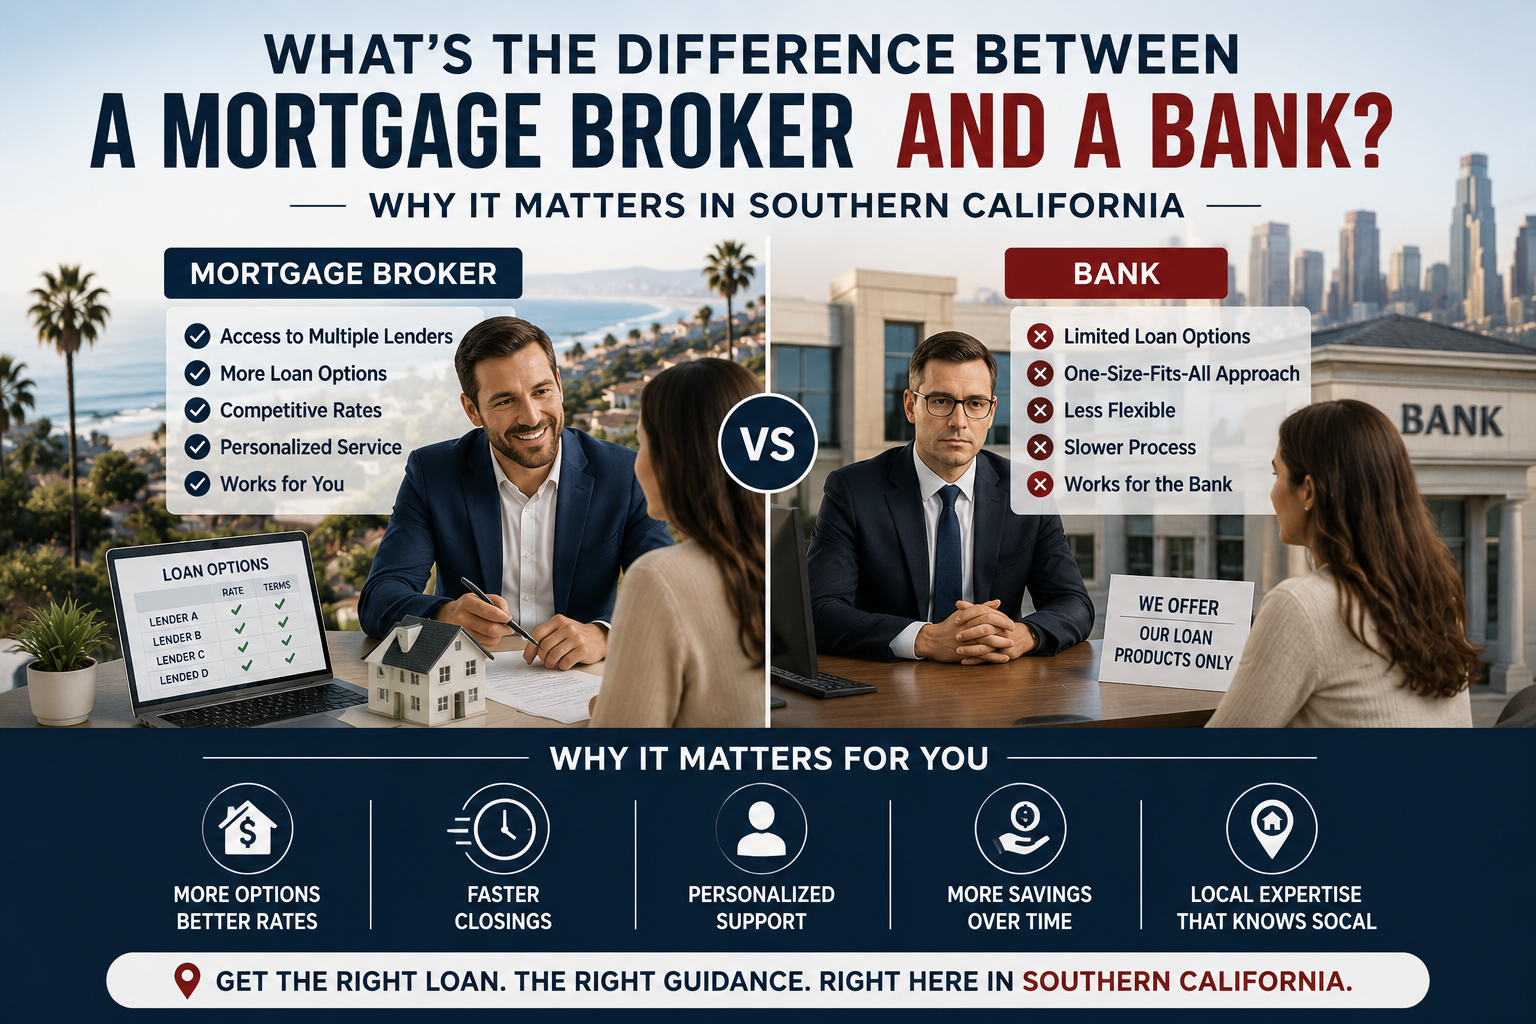

What’s the Difference Between a Mortgage Broker and a Bank? Why It Matters in Southern California
This question comes up in almost every first conversation I have with a new buyer, and it’s a fair one. Both a broker and a bank can get you a mortgage. The difference isn’t marketing — it’s structural, and it directly affects your rate, your approval odds, and how smoothly your transaction goes.
Here’s the honest breakdown, not a sales pitch.
Access to One Lender vs. Access to Many
A bank loan officer works for one institution and can only offer that institution’s products, rates, and guidelines. If their bank’s guidelines don’t fit your situation — your credit profile, your income structure, your down payment — there’s often nowhere else for them to take your file. It’s their bank’s rate and their bank’s rules, or nothing.
A mortgage broker works with multiple wholesale lenders simultaneously. Instead of one set of guidelines and one rate sheet, I’m comparing your file against dozens of lenders’ pricing and guidelines to find the best fit — not just the best available option at a single institution.
This isn’t a small distinction. Two different lenders can look at the exact same borrower and offer meaningfully different rates, different loan programs, and different approval decisions, because their internal risk models and current pricing differ. A bank can only tell you what their one model says. A broker can tell you what the market actually says.
How I Actually Shop Rates for Each Borrower
This is the part that’s easy to say and harder to actually do well, so here’s what it looks like in practice: when I take on a client, I’m looking at your specific profile — credit score, income type, down payment, property type, timeline — and matching that against which lenders in my network are currently most competitive for that exact combination of factors.
Lenders adjust their pricing constantly based on their own capacity, their current pipeline, and which loan types they want more or less of in a given month. A lender that’s aggressively priced for VA loans this month might not be next month. A lender that’s great for self-employed borrowers might not be the best fit for a W-2 employee with a 760 credit score. Shopping across lenders means your rate reflects who’s actually competitive for your specific file today, not a single bank’s static rate sheet.
Why One Lender’s “No” Doesn’t Mean No
This might be the single most important practical difference. If a bank’s underwriting guidelines don’t fit your situation — maybe your income is harder to document, maybe your credit event needs an extenuating circumstances exception, maybe your property type is unusual — that bank simply says no, and you’re back to square one.
As a broker, if one lender in my network declines a file or their guidelines don’t fit, I can take that same file to a different lender whose guidelines are built for exactly that situation. I see this constantly with self-employed borrowers, buyers with a past short sale or foreclosure working through extenuating circumstances, and veterans running into an individual lender’s VA overlay rather than an actual VA rule. A “no” from one institution is information, not a verdict — and having other doors to knock on matters enormously when you’re on a timeline.
Speed and Communication
Banks often route your file through multiple internal departments and layers, with your loan officer having limited direct influence once it moves into processing and underwriting. Response times can be slow, and getting a straight answer sometimes means waiting on someone else’s timeline.
As a broker working your file directly, I’m typically more hands-on throughout the process — tracking where your file sits, following up with underwriting directly, and being the person who actually answers when you call or text with a question, rather than routing you through a general customer service line. In a competitive Southern California market where speed on pre-approval and clear communication during escrow can be the difference between winning and losing a home, this isn’t a minor convenience.
Products Banks Often Don’t Offer
Retail banks tend to stick to a narrow set of standard products — typically conventional and maybe FHA. Two categories in particular are often missing entirely from a bank’s offerings:
VA loans. Many retail banks either don’t originate VA loans at all or handle a low enough volume that their staff isn’t deeply experienced with VA-specific nuances — entitlement calculations, funding fee exemptions, or how to properly position a VA offer in a competitive multiple-offer situation.
Non-QM loans. These are loans built for borrowers who don’t fit standard Fannie Mae, Freddie Mac, FHA, or VA guidelines — self-employed borrowers with complex income, investors using DSCR financing, or buyers who need to purchase before a waiting period from a past credit event has elapsed. Most banks simply don’t offer these products, because they only sell loans that fit standard guidelines.
If your situation touches either of these categories, working with someone who has access to them from the start — rather than finding out after a bank declines you — saves real time and stress.
The Honest Bottom Line
A bank isn’t a bad option for every borrower — if you have a straightforward W-2 income, strong credit, and a standard conventional purchase, a bank can absolutely get the job done. But for buyers whose situation has any complexity at all — self-employment, a past credit event, VA benefits, investment property, or simply wanting to know your rate is actually competitive rather than just accepted — a broker’s access to multiple lenders is a structural advantage a single bank can’t replicate.
Let’s See What Fits Your Situation
Whether your file is straightforward or has some complexity to it, send me your situation and I’ll tell you honestly which lenders in my network are the strongest fit — and what that means for your rate, your approval odds, and your timeline.
Adam Tice Senior Loan Officer, Mark 1 Mortgage — Team Tice NMLS #289398 📞 626-825-2326 ✉️ adam@adamtice.com 🌐 adamtice.com

Comments are closed